Krispy Kreme raises guidance as refranchising bites revenue
Third-quarter net revenue fell 12.4% after a wave of store refranchising, but systemwide sales grew and the doughnut chain raised its full-year outlook.
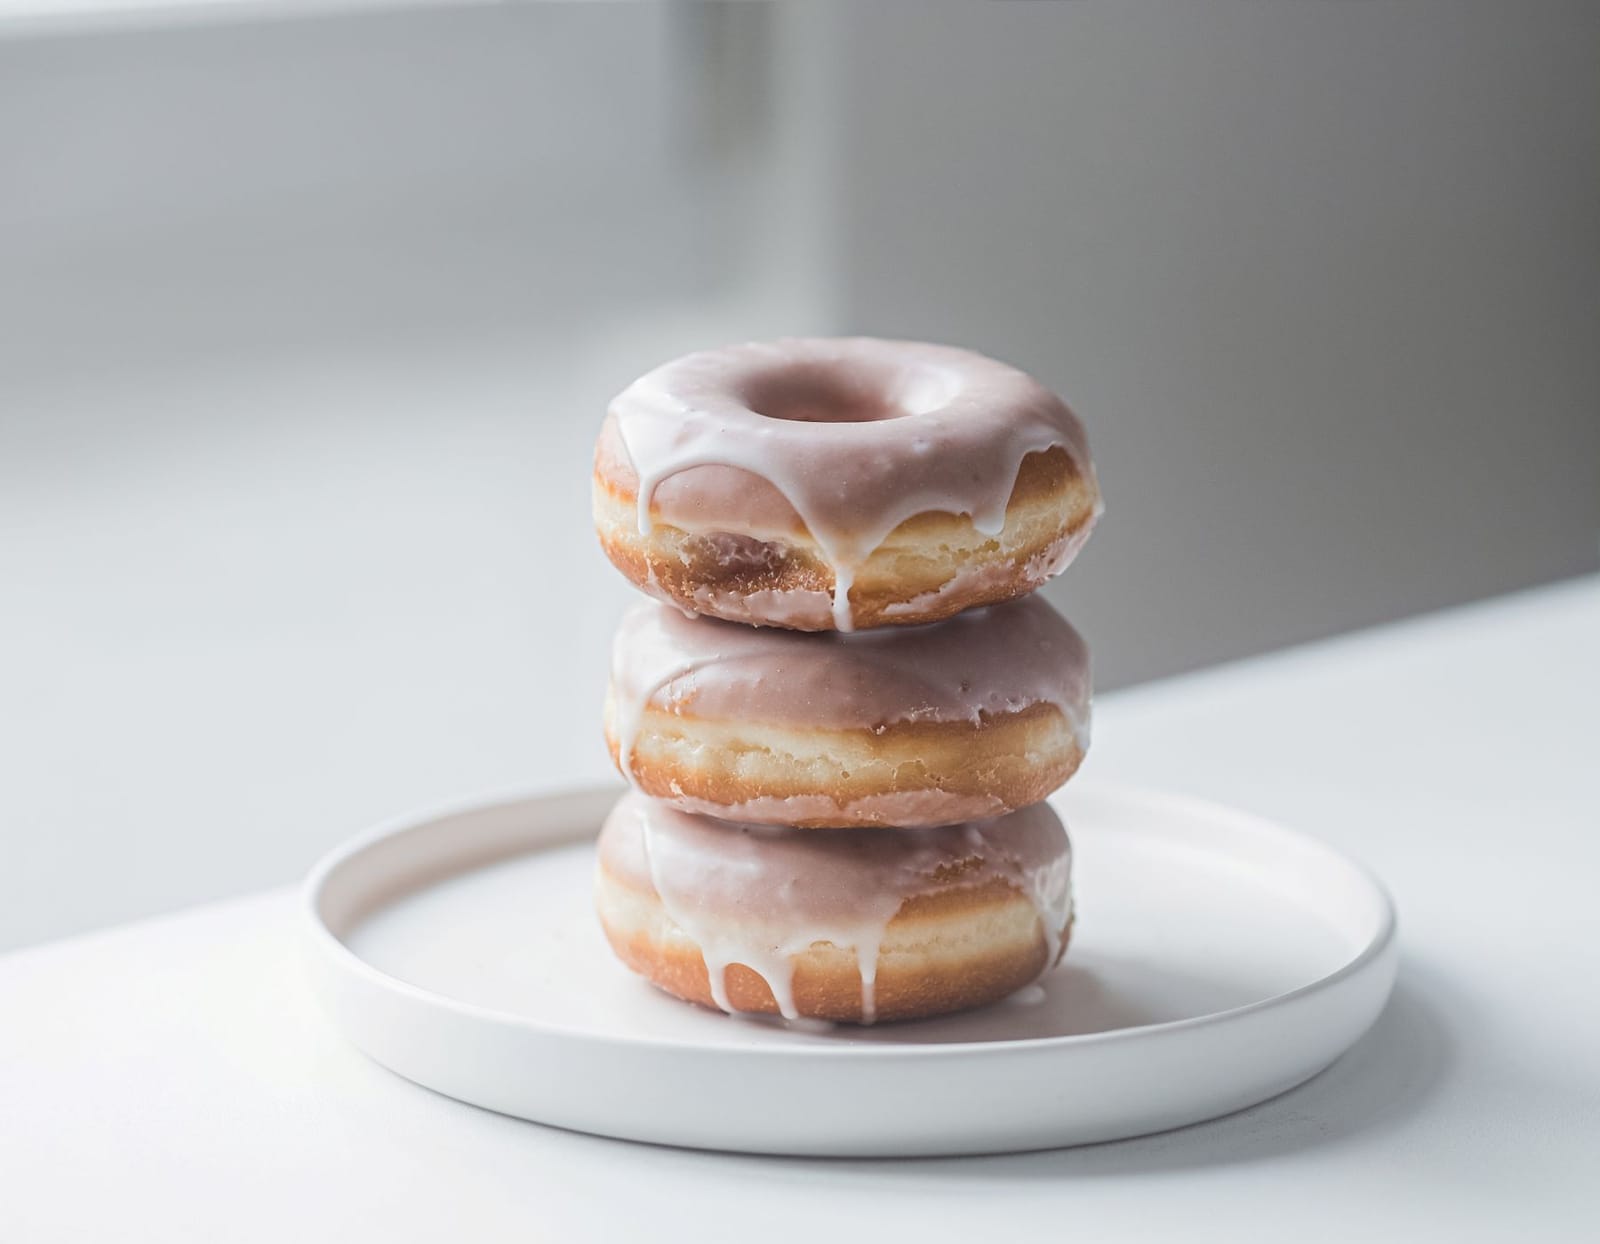
Krispy Kreme guidance for the full year went up on 5 November, even as third-quarter net revenue fell 12.4% to $328.8m. The Charlotte-based doughnut chain said the drop was mostly the result of earlier deals that handed company-owned shops to franchisees.
Systemwide sales, which count doughnuts sold through franchised shops no longer on Krispy Kreme's own books, rose 1.0% in constant currency to $490.2m. The gap between the two numbers shows how far the refranchising push has gone this year.
The GAAP net loss narrowed to $13.3m for the quarter, from a wider loss a year earlier. Adjusted EBITDA came in at $35.3m, up 12.7% once a one-off $9.3m insurance recovery booked in the prior-year quarter is stripped out; including it, adjusted EBITDA fell 13.1%.
The refranchising math finally produced the number that matters: less cash going out the door.
Year-to-date free cash flow stood at roughly negative $10m, an improvement of $82m on the first three quarters of 2025. For a chain that spent much of the past two years explaining away cash burn, that swing is the number investors wanted.
Krispy Kreme's shares jumped more than 6% in pre-market trading, as investors read the raised, narrower revenue range as evidence the refranchising strategy is paying for itself. The contrast with Starbucks, whose US sales rose 7.9% last quarter, shows chains taking very different roads to growth.
Refranchising reshapes the numbers
Krispy Kreme spent 2026 converting company-run shops into franchised ones, a move that trims reported revenue but shifts labour, rent and staffing risk onto franchise partners, mirroring a path other chains take when margins come under pressure.
A franchised shop still sells doughnuts under the Krispy Kreme name, and systemwide sales capture that, but the company itself books a smaller, steadier royalty instead of the full receipts and costs of running the till. Not every chain gets that luxury: Portillo's is closing up to nine restaurants outside Chicago rather than handing them to franchisees.
What the turnaround still needs to prove
Free cash flow, not revenue, has been the metric management pointed to most this year, and the $82m improvement is the clearest evidence yet that the refranchising plan is working as intended.
Strip out last year's one-off insurance recovery and adjusted EBITDA improved; leave it in and the comparison looks worse. Krispy Kreme has not disputed either calculation, suggesting the gap is presentation rather than dispute. Guidance now points to a narrower, higher range than in August, with management confident in the turnaround's direction.